Why ‘Moneymaxxing’ Can Boost Your Savings but Going Too Far Can Cost You More Than It Saves!
Saving money has a new social media name, and it sounds much more exciting than balancing a budget. The trend is called ‘moneymaxxing’, and the basic idea is simple. You try to squeeze more value from the money you already have. That could mean moving cash into a higher-yield savings account, cutting forgotten subscriptions, earning credit card rewards, negotiating bills, or spending more carefully.
The term comes from the internet habit of adding ‘maxxing’ to almost anything people want to optimize. ‘Looksmaxxing’ focuses on appearance, while ‘sleepmaxxing’ focuses on sleep. Now personal finance has joined the same trend, although most ‘moneymaxxing’ tactics existed long before social media gave them a catchy label.
Why ‘Moneymaxxing’ Has Caught On

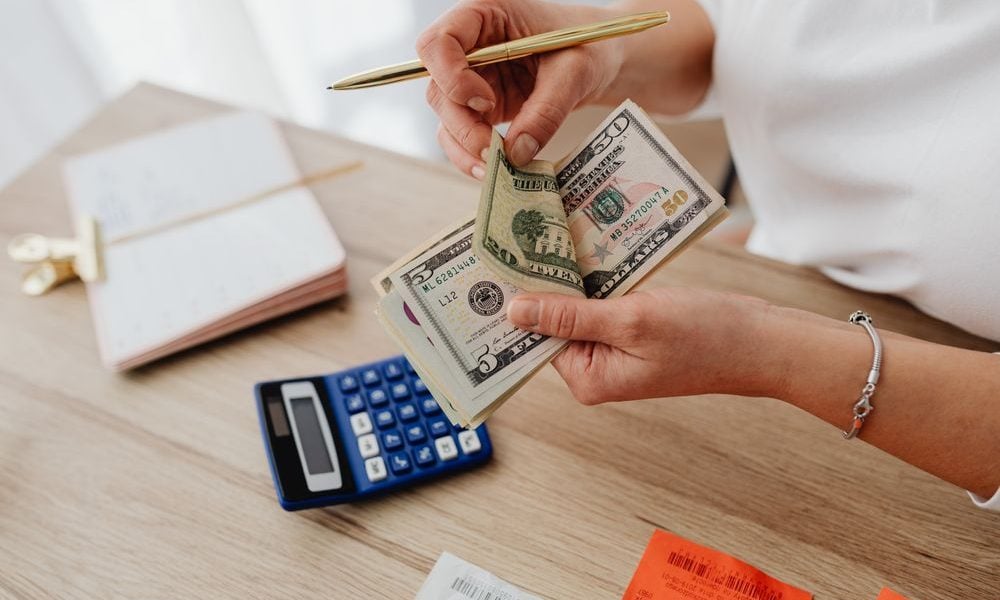
Tim / Pexels / Northwestern Mutual’s 2026 Planning & Progress Study found that 72% of Gen Z and 53% of millennials are not fully financially independent from their parents.
Per the study, Americans also said they achieved, or expect to achieve, financial independence at an average age of 37.
The strongest ‘moneymaxxing’ moves are also surprisingly ordinary. Moving idle savings into an account paying a competitive interest rate can increase earnings without requiring more work. Reviewing subscriptions can stop money from disappearing each month for services nobody uses anymore.
Credit card rewards can provide value too, but only when they reward purchases someone already planned to make. Spending $500 on groceries and getting cash back is better than spending the same $500 without earning anything. The purchase still needs to fit the household budget.
Northwestern Mutual describes ‘moneymaxxing’ as an effort to make every dollar work as effectively as reasonably possible. Its guidance recommends starting with a clear picture of monthly income, fixed expenses, variable spending, savings, and debt. That basic snapshot can show where meaningful improvements actually exist.
When ‘Moneymaxxing’ Starts Costing You Money?
/ Pexels / Chasing tiny differences in savings rates can create extra accounts, transfers, passwords, statements, and rules to manage.
Consider someone with $10,000 in savings who finds another bank paying 0.20% more. Ignoring compounding and taxes, that difference produces only about $20 of additional interest over a year. Moving the money could still make sense, but the benefit needs to justify the effort and any conditions attached to the account.
A much bigger rate difference deserves more attention. Leaving thousands of dollars in an account paying almost nothing when competitive savings accounts pay substantially more can mean giving up meaningful interest. ‘Moneymaxxing’ works best when it targets large gaps instead of microscopic ones.
Credit card ‘pointsmaxxing’ creates another trap. Rewards feel like free money, which can make an unnecessary purchase easier to justify. A shopper might spend $100 simply because a card offers extra points in that category, even though skipping the purchase would have saved the entire $100.
Carrying credit card debt makes the calculation even worse. Rewards can lose their value quickly when interest starts piling up on an unpaid balance. Earning a few percentage points in cash back does little good when borrowing costs are substantially higher.
Good ‘moneymaxxing’ should make financial life easier over time. If someone constantly checks rates, moves tiny balances, tracks complicated reward categories, and worries about squeezing another dollar from every purchase, the system has started working against them.
Saving Every Penny Is Not the Same as Building Wealth
The biggest weakness in ‘moneymaxxing’ may be its heavy focus on saving. Mical Jeanlys-White, founder of WealthMore, told CBS News that the conversation often centers on finding places to save while overlooking another question: how to put that money to work?
Jeanlys-White argues that investing needs to enter the conversation. Money directed toward suitable long-term investments has the potential to compound over time, although investment returns are never guaranteed and values can fall. The longer the time horizon, the more important compounding can become.
More inAdvice
-
`
 Auto.m Autonomous Taxi Concept Wins 2026 Red Dot Award
Cities are exploring new ways to improve transportation as demand grows for cleaner, smarter, and more convenient mobility solutions. Autonomous vehicles...
August 1, 2026 -
`
 Olympic Cyclist Pleads Guilty to Driving While Banned After Crash That Killed His Wife
Former Olympic cyclist Rohan Dennis has admitted to driving while disqualified, adding another chapter to a case that has drawn attention...
July 30, 2026 -
`
 Tesla’s Miami Robotaxi Launch Is Big News, but Will It Lift TSLA Stock?
Tesla continues to attract attention from both active traders and long-term investors, making TSLA one of the most closely watched stocks...
July 26, 2026 -
`
 All the Reasons Why You Shouldn’t Blindly Follow AI Money Advice
Artificial intelligence has quickly become part of everyday life. People now use AI to write emails, plan vacations, answer questions, and...
July 24, 2026 -
`
 Financial Advice From Millionaires That Could Actually Hurt Your Wallet
Money advice from millionaires often sounds convincing because it comes from people who have already built wealth. Still, success does not...
July 19, 2026 -
`
 Do You Really Need Rental Car Insurance? A Deeper Look
Renting a car feels simple until the person at the counter starts asking about insurance. Many travelers freeze at that moment...
July 17, 2026 -
`
 What Qualifies a Vehicle for Classic Car Insurance?
Owning a classic car is about more than preserving an older vehicle. Many enthusiasts appreciate vintage automobiles because they are easier...
July 12, 2026 -
`
 NHTSA Launches ‘Special Investigation’ After Fatal Tesla Crash Into Texas Home
A deadly Tesla crash in Texas is now at the center of a federal safety investigation. The U.S. National Highway Traffic...
July 8, 2026 -
`
 “Grand Theft Auto VI” Cover Art Revealed
Rockstar Games gave fans a fresh look at “Grand Theft Auto VI” after releasing the game’s official cover art on Thursday....
July 5, 2026
More From CashRoadster
-
 Why ‘Moneymaxxing’ Can Boost Your Savings but Going Too Far Can Cost You More Than It Saves!
Saving money has a new social media name, and it sounds much more exciting than balancing a budget. The trend is...
AdviceOctober 15, 2026 -
 Simone Biles Says Three Masked Men Stole Her Six-Figure Porsche
Simone Biles has shared details about a frightening incident that happened during her final months in Chicago. The Olympic gold medalist...
AdviceOctober 10, 2026 -
 How to Lower Your Car Insurance Premium Without Dropping Essential Coverage?
Car insurance can feel painfully expensive, especially when your driving record has not changed. You renew the same policy, drive the...
Car InsuranceOctober 8, 2026 -
 California Proposes New Auto Insurance Rules for Single Drivers
California drivers could see a change in how auto insurance companies set premiums. Insurance Commissioner Ricardo Lara has announced a proposed...
Car InsuranceOctober 4, 2026 -
 Credit Acceptance Pays $710 Million to Settle Predatory Auto Lending Claims
One of America’s largest subprime auto lenders has agreed to a massive settlement over allegations that it put financially vulnerable drivers...
Auto NewsOctober 1, 2026
You must be logged in to post a comment Login